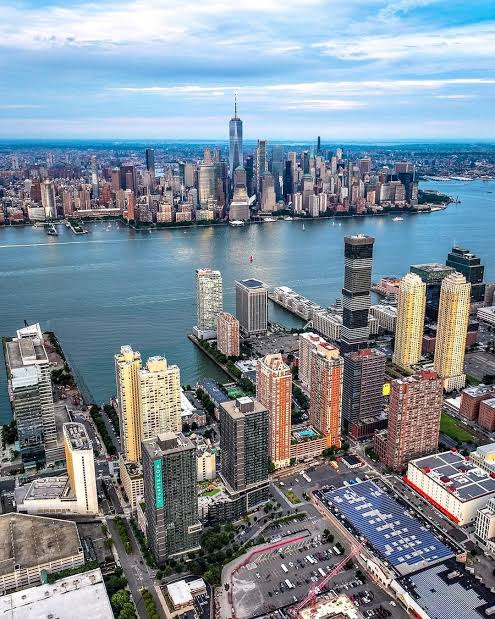
Cross the Hudson, and the same money buys more. That's the pull. But whether the move actually pays off depends on three numbers that fight each other, not the one on the listing.
If you're weighing a purchase in Jersey City after years of renting or owning in New York, you've probably read conflicting takes. One post calls Jersey City a bargain. The next warns the property taxes will eat you alive. Both are partly right, which is exactly why buyers get stuck.
Short answer: For most NYC buyers, yes, Jersey City works. The median home runs about $710,000 versus $870,000 in NYC, roughly 22% lower. Eliminating NYC's ~3.8% resident income tax often offsets Jersey City's higher property tax. The real answer depends on your total monthly carry, not the sticker price.
This is an honest, numbers-backed walkthrough of the real estate decisions (price, taxes, commute, process, neighborhood), not a pitch for the move.
How Much Cheaper Is Jersey City, and Is the Gap Widening?
Jersey City runs about 22% below NYC on median price, and the gap is growing.
Over the six months ending July 2026, the Jersey City median sold price was roughly $710,000 across 748 closed sales. NYC's median was $870,000 in January 2026. That's a dollar gap of about $160,000.
Here's the part that changes timing: the gap is widening. NYC prices rose 2% year over year while Jersey City sits flat-to-down, and Redfin shows a $720,000 median, off 1.4%. Flat prices don't mean waiting pays. They mean it's a balanced market where you shouldn't overpay on Manhattan logic.
What does the gap buy? More space and more property types. Jersey City isn't just high-rise condos. You'll find boutique condos, brownstones and rowhouses, two-family homes, and new developments. Manhattan new-dev condos averaged over $2,000 per square foot in late 2025; comparable Downtown Jersey City product traded in the mid-$800s. Patrick's developer lens helps you judge how a new unit was priced, which floor plans are efficient, and whether the amenities justify the premium.
What's Your True Monthly Cost After Taxes?
The biggest mistake NYC buyers make is comparing purchase prices without calculating full carrying costs. Three variables pull in opposite directions.
The three opposing numbers:
Purchase price favors Jersey City by ~$160,000
Property tax favors NYC (higher in JC on non-abated units)
Income tax favors Jersey City by $9,000 to $20,000/year
Jersey City's 2025 general rate is 2.335% of assessed value, and NJ assesses near market value. On a $700,000 non-abated condo, that's about $16,345 a year, roughly 2 to 3 times a comparable abated NYC condo, which typically pays $8,000 to $12,000. Many newer towers carry PILOT agreements (Payments In Lieu of Taxes) that cut the early-year burden to 1.0 to 1.5%. Verify the specific tax bill and the PILOT expiration date, because the number steps up, sometimes sharply, when it ends.
Here's the number most guides miss. Moving to New Jersey eliminates NYC's resident income tax of roughly 3.078% to 3.876%. At $250,000 of income, that saves $9,000 to $10,000 a year; at $500,000, about $19,000 to $20,000, even if you still commute to Manhattan. That offset frequently erases the higher property tax entirely.
How Long Is the PATH Commute, Really?
Most Jersey City to Manhattan commutes run 20 to 35 minutes door to door, but your station matters more than any average.
The honest downside is weekends. Grove Street sees about 27 trains per hour at peak but only 6 on weekends. Crowding is rising, too. PATH carried 60.7 million riders in 2025, and June 2026 was its busiest month since March 2020.
Reliability is decent, not perfect. On the Newark to WTC line, 77% of riders said their last trip arrived on time, meaning about 1 in 5 trips may hit a delay. You can buy down your commute. A short walk to Exchange Place is a completely different daily life than a bus-plus-PATH transfer from an interior block. Ride your actual trip at rush hour before you commit.
How Is Buying in New Jersey Different From NYC?
New Jersey's process is mechanically simpler and cheaper, with one exception at the top of the market.
Key differences from NYC:
Attorney review: NJ has a mandatory 3-business-day review after a signed contract, when either attorney can revise or cancel for any reason. NYC negotiates before you sign.
Closing costs: ~1 to 3% in northern NJ versus 2 to 5% in NYC.
Mortgage recording tax: None in NJ. NYC's adds roughly $35K to $45K on large loans.
Mansion Tax: Above $1M, NJ's graduated tax applies, 1% from $1M to $2M, rising to 3.5% over $3.5M, paid by the buyer.
The bigger structural shift: ownership type. About 75% of NYC for-sale inventory is co-ops; Jersey City is almost entirely condos with individual deeds. No board package, no board interview, easier financing, simpler resale.
That doesn't mean skip diligence. Not every building is equal. Scrutinize HOA charges and reserves. Jersey City fees run about $300 to $600/month for smaller walk-ups and $600 to $1,200+ for amenity towers.
Which Jersey City Neighborhood Fits You?
Treating all of Jersey City as equally Manhattan-convenient is the core buyer error. It isn't. Days-on-market swings from 14 days Downtown to 40-plus in Bergen-Lafayette.
Match by origin:
From Manhattan, wanting speed → Downtown or Paulus Hook
From Brooklyn, wanting space and value → The Heights or Journal Square
Buying with future-rental optionality → Journal Square, with the strongest gross yield at 6.6% versus 4.5% Downtown
Patrick's positioning work matches product type, price, and resale prospects to your specific profile.
Are You Giving Something Up?
Less than most New Yorkers fear, and the numbers back that up.
Jersey City earns an overall A grade on Niche, with A+ for Diversity and A- for families. Its Walk Score of 87 ranks it the 3rd most walkable US city, behind San Francisco and New York. Nearly 100% of residents live within a 10-minute walk of a park, a real advantage for families.
Safety is honest and neighborhood-dependent. Niche gives a C- overall: above-average assault and robbery rates, below-average murder and rape. Downtown and Paulus Hook rank among the safest areas.
This move is well-trodden. Over 75,000 New Yorkers relocated to New Jersey in 2024, up 12% year over year, with Hudson County a top landing spot.
On competition: June 2026 showed a 17-day median days-on-market, ~6 months of supply, and 48% of closings at or above ask. Condos are balanced; single-family homes are a tight seller's market at just 3.4 months of supply. Price your offer to the neighborhood, not to Manhattan logic.
Frequently Asked Questions
Is buying in Jersey City cheaper than NYC?
Yes. The Jersey City median ran about $710,000 to $760,000 in mid-2026 versus $870,000 in NYC, roughly 22% lower. The gap is widening as NYC continues to appreciate and Jersey City stays flat.
Are Jersey City property taxes really 2-3x higher?
On non-abated units, usually yes. The rate is 2.335% of assessed value versus an effective ~1% in NYC after abatements. But PILOT buildings drop that to 1.0 to 1.5% in early years (check the expiration date).
Does moving to New Jersey save on income tax?
Yes, and this is the number most people miss. You stop paying NYC's ~3.8% resident tax, saving roughly $9,000 to $20,000 a year depending on income, even if you still work in Manhattan.
Do Jersey City buildings have co-op boards?
No. Jersey City is almost entirely condos. That means no board approval, easier financing, and simpler resale than a NYC co-op.
Should I move from Brooklyn or Manhattan, does it differ?
It does. From Manhattan, prioritize commute speed (Downtown, Paulus Hook). From Brooklyn, you're usually chasing space and value (The Heights, Journal Square).
Should You Make the Move?
For many New Yorkers, Jersey City delivers more space and a lower price while keeping Manhattan minutes away. The trade-offs are real: higher taxes on non-abated units, thinner weekend PATH service, safety that varies by block.
The full picture includes the offsets: the eliminated NYC income tax, lower closing costs, no mortgage recording tax. That's why the sticker-price comparison misleads so many buyers.
One rule decides it: model your total monthly carry before you commit, mortgage plus taxes (or PILOT) plus HOA, netted against the income-tax savings. Then get local eyes on the specific building and neighborhood.
For senior Jersey City market context on pricing, positioning, and new-development value, talk to Patrick Southern.